By Keith Wong, FAR (BNM) · IFAR (BNM) · LFP (SC)
Table of Contents
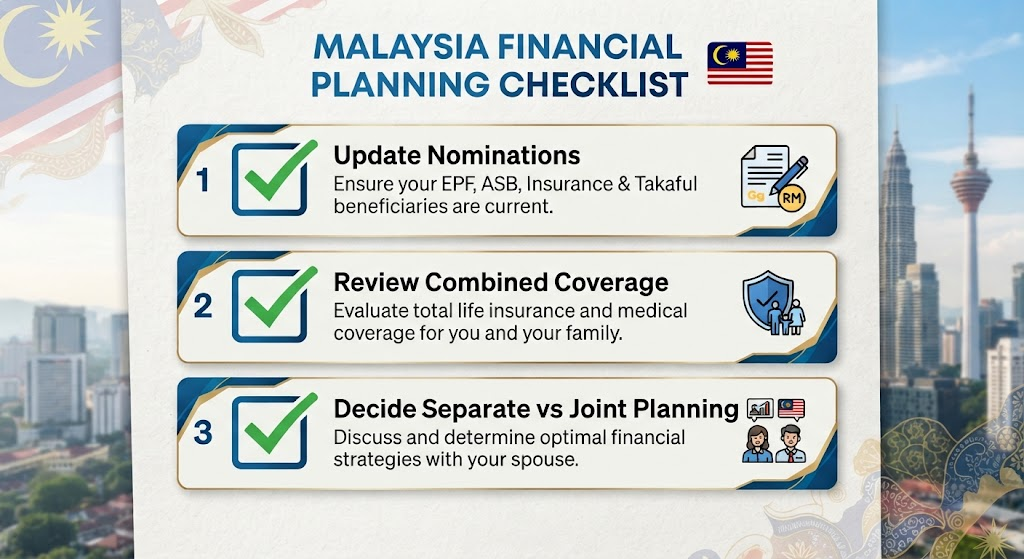
Quick Answer: Your insurance checklist before marriage Malaysia should cover three things before the wedding, not after: updating nomination on every existing policy and EPF, reviewing whether your combined household needs more medical or life cover than you each carry separately, and deciding whether to keep policies separate or consolidate. None of this needs to be finished before the ceremony — but it should be started before it, while you’re already reviewing paperwork for the marriage itself.
Most engaged couples in Malaysia spend months on the venue, the photographer, and the guest list, and zero time on the insurance paperwork that quietly becomes outdated the moment they marry. It’s an easy thing to skip — nobody wants to talk about critical illness cover during wedding planning — but this is genuinely one of the cheapest, fastest pieces of the whole process to get right, and one of the most expensive to get wrong years later.
Insurance Checklist Before Marriage Malaysia — The Three Things That Matter
This insurance checklist before marriage Malaysia list isn’t long, but each item has a real cost attached if it’s ignored — either a payout going to the wrong person, or a gap in cover neither of you notices until it’s needed.
1. Update Every Nomination — Not Just Life Insurance
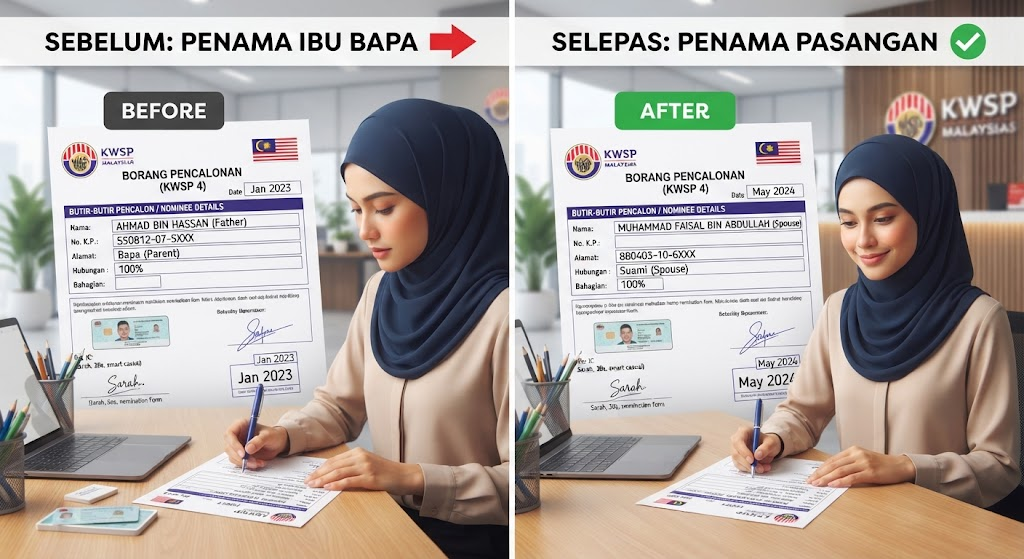
Every life insurance policy, medical card with a death benefit rider, and your EPF account has a nomination attached — and marriage doesn’t automatically update any of them. If your nomination still names a parent or an ex-partner from before the relationship, that’s who legally receives the payout, regardless of what your spouse assumes will happen. This is the single fastest item on this list: it costs nothing and takes an afternoon of paperwork with each insurer plus an EPF nomination update.
2. Review Combined Medical and Life Coverage
Two individually-insured people don’t automatically have adequate household coverage once they combine finances and (often) debt. If one spouse’s income now supports a joint mortgage or a future family, that spouse’s life insurance should be reviewed against the new joint liability, not just their old single-person number. Medical cards are also worth comparing side by side — if one of you has a stronger panel of hospitals or a lower co-payment, it’s worth understanding why before assuming both are equally adequate.
3. Decide: Separate Policies or Consolidate?
There’s no universally correct answer here — some couples keep every policy fully separate for simplicity, others consolidate onto one insurer for potential family/bundling discounts and simpler bill management. What matters is making this a deliberate decision rather than defaulting into it because nobody discussed it before the wedding.
Why This Matters More Than It Seems Right Before a Wedding
None of this feels urgent while you’re deep in wedding logistics, which is precisely why it gets skipped so often. But an outdated nomination or a coverage gap doesn’t announce itself — it sits quietly until a claim actually happens, at which point it’s too late to fix. Going through an insurance checklist before marriage Malaysia takes an afternoon. Untangling a nomination dispute or a coverage gap after the fact can take months, and sometimes it can’t be untangled at all.
If Faith or Structure Matters: Consider Takaful Together
If either of you is weighing takaful over conventional insurance for religious or structural reasons, marriage is a natural point to align on this as a couple rather than each defaulting to whatever you individually held before. We’ve covered the actual contractual difference between the two in detail separately — worth a read together if this is a factor in your decision, since it affects how any surplus is treated and how the underlying contract works, not just which panel of hospitals you can use.
A Simple Timeline for Getting This Done
You don’t need to solve all of this in one weekend. A realistic timeline: update nominations on existing policies within the first month of engagement (it’s the fastest item and has no dependency on anything else), review combined medical and life coverage together two to three months before the wedding once your joint financial picture is clearer, and make the separate-vs-consolidate decision any time in the first year of marriage — there’s no cutoff forcing that one before the ceremony itself.
Do we need to combine our insurance policies once married?
No, there’s no requirement to consolidate. Many couples keep policies fully separate. The important step is reviewing coverage and nominations together, not necessarily merging providers.
Does getting married automatically change my EPF nomination?
No. EPF nominations don’t update automatically on marriage, divorce, or any other life event — you have to submit the change yourself. An outdated nomination remains legally valid until you change it.
Should we buy life insurance together or separately?
Life insurance is always underwritten and owned individually in Malaysia — you can’t buy one joint policy the way you might get joint home financing. What you can do is coordinate the sums insured so combined cover matches your actual combined liabilities and goals.
Planning a Wedding? Get the Insurance Side Sorted in One Session
I can walk you both through nominations, combined coverage review, and what’s actually worth consolidating — in one sitting, before the wedding admin takes over. WhatsApp me at +6016-336 9321.
Disclaimer: This article is for general informational purposes only and does not constitute financial or insurance advice. Nomination rules, entry requirements, and product terms vary by insurer and by EPF’s current procedures — always confirm directly with the relevant provider. Keith Wong is a Financial Adviser’s Representative (FAR) and Islamic Financial Adviser’s Representative (IFAR) licensed under Bank Negara Malaysia, and a Licensed Financial Planner (LFP) under the Securities Commission Malaysia.