By Keith Wong, FAR (BNM) · IFAR (BNM) · LFP (SC)
Most SME loan rejections come down to a handful of recurring issues. Here’s what banks are really screening for before they say no — and what to fix before you reapply.
Table of Contents
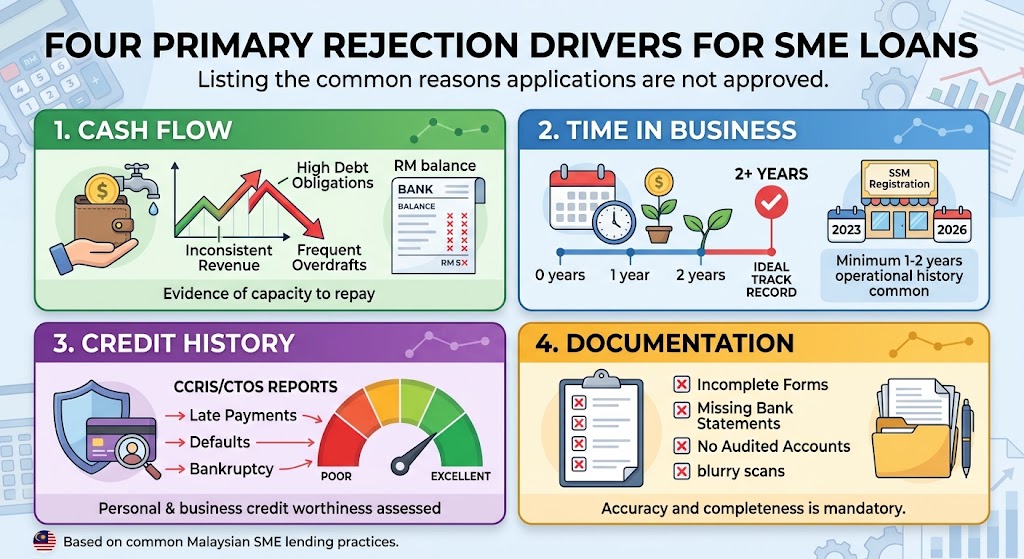
SME loan rejected Malaysia reasons usually come down to four recurring issues: inconsistent cash flow, too little time in business, poor personal credit (CCRIS/CTOS records), and incomplete documentation. A rejection isn’t usually a verdict on your business itself — it’s more often a sign the numbers or the paperwork didn’t give the bank enough confidence in your ability to repay.
Getting turned down for an SME loan feels personal, especially when the business itself is doing fine. But bank credit decisions aren’t really a judgement on whether your business is good — they’re a judgement on whether the application, as submitted, gave the bank enough confidence that repayment is low-risk. Those are two very different things, and the gap between them is usually fixable.
Why SME Loan Rejections Are So Common in Malaysia
A large share of first-time SME financing applications in Malaysia get declined, and it happens to well-run, profitable businesses more often than owners expect. Part of the reason is structural: banks are lending against numbers and documents, not against how the business actually feels from the inside. If the paperwork doesn’t clearly tell the story a credit officer needs to see, the safest decision for the bank is to decline rather than dig further.
The 4 Most Common Reasons Banks Say No
1. Inconsistent cash flow
This is the single biggest red flag for most lenders. Even a business with healthy sales can look risky if collections are slow, revenue swings sharply month to month, or bank statements show irregular deposit patterns. Banks want to see cash flow that’s predictable enough to comfortably cover a new loan repayment on top of existing commitments — not just proof that money came in at some point during the year.
2. Insufficient time in business
Most banks want to see at least 2 years of consistent operating history before extending standard SME financing, since a shorter track record gives them very little data to assess repayment risk against. Newer businesses aren’t automatically disqualified, but they’re usually a better fit for government-backed or DFI schemes designed for early-stage SMEs, rather than a standard commercial facility.
3. Poor personal credit history (CCRIS/CTOS)
For most SMEs, especially sole proprietorships and smaller Sdn Bhds, the bank looks closely at the director’s or owner’s personal credit record — not just the company’s. Even a fully settled default from years ago can trigger a decline if it isn’t explained upfront, because an unexplained CCRIS or CTOS entry reads as unmanaged risk rather than a one-off event.
4. Incomplete or poorly presented documentation
A surprising number of rejections have nothing to do with the underlying business — the application itself was incomplete, inconsistent, or missing supporting documents. A typical submission requires the SSM registration and latest annual return, director’s NRIC, 2 years of financial statements, 6 months of business bank statements, a CCRIS printout, and an existing borrowing schedule. Missing even one item, or submitting numbers that don’t reconcile across documents, is often enough to trigger a decline rather than a request for more information.
What Banks Are Really Screening For
Underneath the paperwork, banks are essentially asking one question: if they lend this money, how confident are they it comes back on schedule? That confidence is built from a few specific checks:
- Debt service ratio — whether your existing repayment commitments, plus the new loan, still leave a comfortable buffer against your income
- Cash flow trend — whether revenue and collections are stable or improving, not just whether the business is profitable on paper
- Credit history — both the business’s and, in most SME cases, the owner’s or directors’ personal CCRIS/CTOS records
- Collateral or security — what backs the facility if things go wrong, and how that compares to the loan amount requested
- Lender fit — some banks and DFIs are simply a better match for certain industries, business ages, or loan sizes than others, so the ‘wrong lender for your profile’ can itself be the reason for a decline
What to Do After a Rejection
- Ask the bank for the general reason for decline — most won’t give a detailed breakdown, but many will share a general category if you ask directly
- Pull your own CCRIS/CTOS report before reapplying, so you know exactly what a bank will see and can prepare an explanation for anything unresolved
- Fix the root cause rather than reapplying with the same numbers at a different bank — a documentation gap or an unexplained credit entry will likely trigger the same outcome elsewhere
- Consider government-backed schemes — facilities backed by Credit Guarantee Corporation (CGC), SME Bank, or Bank Negara Malaysia’s SME funds often have more flexible criteria for newer or higher-risk businesses
- Get your financial story in order before the next application — clean, reconciled financial statements and a clear explanation of any loss year or irregular period go a long way toward addressing a bank’s underlying concern
Frequently Asked Questions
Can I apply for another SME loan after a rejection?
Yes. A decline from one bank doesn’t bar you from applying elsewhere, and it isn’t recorded as a black mark the way a loan default is. It’s usually worth understanding and addressing the likely reason first, though, rather than reapplying with the same application and hoping for a different outcome.
Does a loan rejection affect my CCRIS or CTOS record?
A rejected application itself isn’t a negative record. What does show up on your credit report is your repayment history on existing facilities and any past defaults — the rejection is simply the bank’s decision, not a mark against you.
What exactly are CCRIS and CTOS, and why do they matter so much?
CCRIS is Bank Negara Malaysia’s Central Credit Reference Information System, and CTOS is a private credit reporting agency — both compile your repayment history across banks and lenders. Since most SME lending also looks at the owner’s personal credit record, an issue on either report can affect a business loan application even if the business itself is financially sound.
Are government-backed SME loans easier to get approved than a standard bank loan?
Often, yes, particularly for newer businesses or those in higher-risk industries — schemes backed by CGC or SME Bank are specifically designed to share or absorb some of the lender’s risk, which can make approval more achievable than a standard commercial facility. Eligibility criteria and facility sizes still vary by scheme, so it’s worth checking which one actually fits your business profile.
If you’d like a second pair of eyes on your financial story before your next SME loan application — or want to understand how your business cash flow holds up against a bank’s usual checks — happy to walk through it with you.
WhatsApp me at +6016-336 9321 and we’ll go through what actually needs fixing before you reapply.
This article is for general information only and does not constitute financial or lending advice. Loan approval criteria vary by bank and lending institution and are subject to change. Please consult the relevant bank or a licensed financial adviser before making any borrowing decisions.