By Keith Wong, FAR (BNM) · IFAR (BNM) · LFP (SC)
Every construction contract in Malaysia requires it — the scope and exclusions are where most gaps hide.
Table of Contents
Quick Answer: Contractors All Risks CAR insurance Malaysia contracts require covers physical loss or damage to the contract works, materials, and construction plant on site, plus third-party liability arising from the works. It’s a contract condition on virtually every project — government or private — so cover has to be in place before mobilisation. The scope and exclusions vary far more between policies than the name suggests, and the exclusion contractors misunderstand most often is design defect, so check policy wording against your actual contract form rather than assuming standard cover is enough.
Contractors all risks CAR insurance Malaysia projects rely on is one of those policies everyone in the industry has heard of but few can explain past the acronym. It shows up as a line item in every tender document and every Letter of Award, and in practice you can’t mobilise to site or draw your first progress payment without proof of it. What catches contractors out isn’t whether they have a CAR policy — almost everyone does — it’s whether the scope of that specific policy actually matches what their specific contract requires.
What CAR Insurance Actually Covers
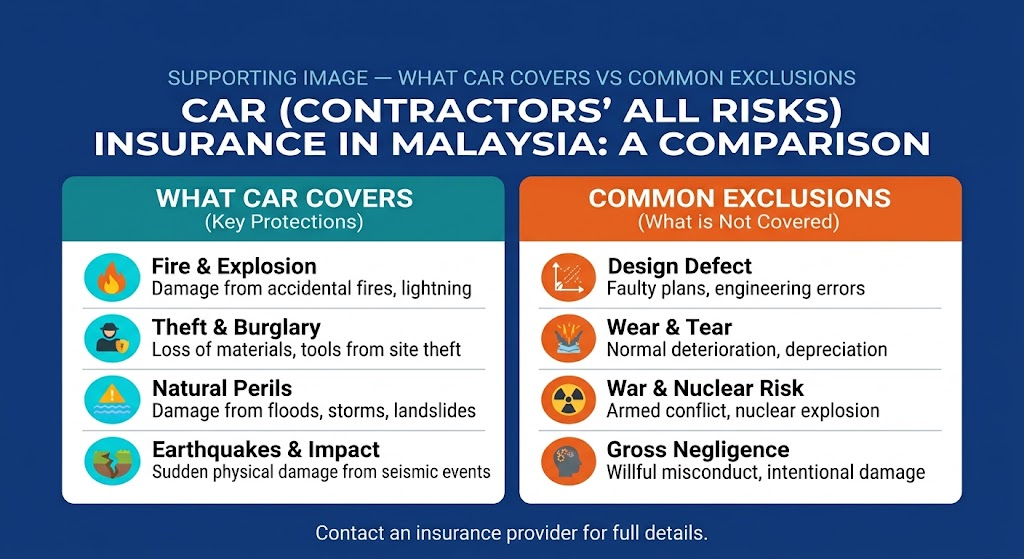
CAR insurance is structured in two main sections that work together. Section I (material damage) covers sudden and unforeseen physical loss or damage to the permanent works, temporary works, and materials on site — fire, flood, theft, and accidental damage during construction. Section II (third-party liability) covers claims from third parties for injury or property damage arising from the construction activity, which matters enormously on sites adjoining public roads, other buildings, or occupied premises.
Almost every construction contract used in Malaysia — PAM, PWD/JKR, CIDB, or FIDIC-based — makes CAR a condition precedent to starting work. Government and private clients alike will ask for proof of cover, usually a Certificate of Currency naming the employer as a joint insured, before releasing the site or the first payment.
The Exclusion Contractors Misunderstand Most
Design defect
If a design flaw causes part of the structure to fail, standard CAR cover pays for the resulting damage to the otherwise sound parts of the works — but it won’t pay to fix or replace the defectively designed element itself. Contractors who assume “all risks” means exactly that are usually surprised by this clause the first time it’s tested on a claim. Where design risk sits with the contractor (design-and-build contracts, for instance), it’s worth discussing a design defect extension with your insurer rather than discovering the gap after a failure.
Wear, tear, and gradual deterioration
CAR responds to sudden, unforeseen events — not gradual deterioration, corrosion, or normal wear from prolonged exposure. A retaining wall that slowly settles due to inadequate drainage design, for example, sits closer to a maintenance or design issue than an insurable event, depending on how it develops.
Getting the Sum Insured Right
A common and costly mistake is insuring only the materials or construction cost, rather than the full contract value. The sum insured should reflect the complete contract sum — materials, labour, plant hire, professional fees, and any employer-supplied materials or plant that fall within the contractor’s care, custody, and control. Under-insuring the sum insured can trigger average (proportionate) clauses at claim time, meaning even a partial loss gets paid out at a reduced percentage relative to how far the sum insured falls short of the true value.
Premium rates for CAR in Malaysia are individually rated against project risk, typically running from roughly 0.15% to 0.6% of contract value — lower for straightforward residential building work, higher for civil engineering, infrastructure, or projects with challenging ground conditions or a compressed programme.
Matching the Policy to Your Contract Form
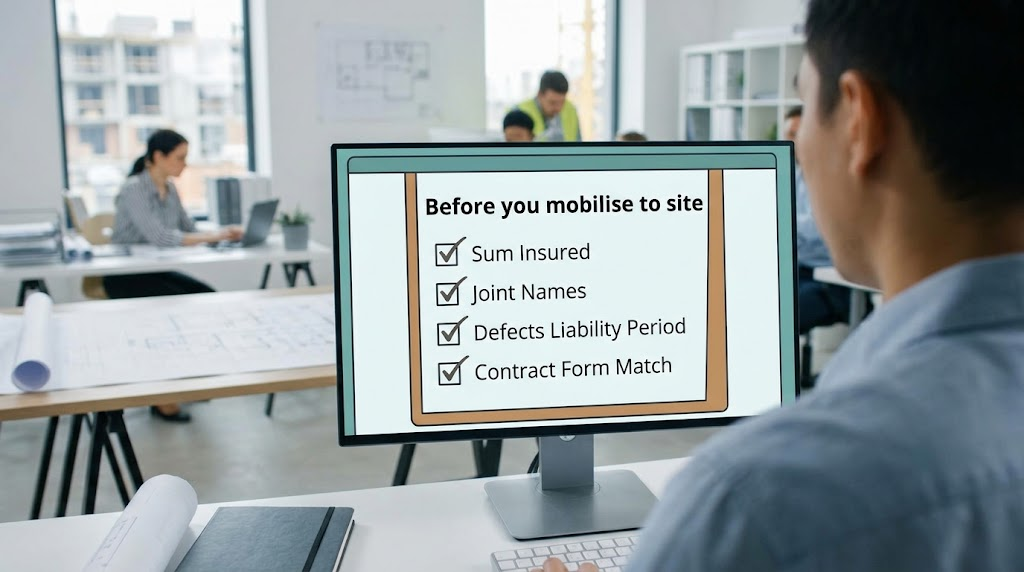
- PAM contracts typically specify joint-names insurance with the employer, and reference a defined defects liability period during which limited cover extends
- PWD/JKR (government) contracts carry their own insurance clauses and documentation requirements distinct from private PAM forms
- FIDIC-based contracts (common on larger or internationally-financed projects) have their own insurance obligations under the general conditions
- Subcontractors named under a main contractor’s CAR policy are often covered for the works but not for their own plant, equipment, or broader business liability — a separate policy is usually still needed
Frequently Asked Questions
Is CAR insurance a legal requirement in Malaysia?
Not directly under a single piece of legislation, but it’s effectively mandatory in practice — virtually every construction contract, government or private, makes it a condition of mobilising to site and receiving progress payments. CIDB registration also expects contractors to demonstrate adequate insurance arrangements.
Does CAR insurance cover the contractor’s own plant and machinery?
Construction plant and equipment on site can be included, but it’s often a separate section or extension with its own sum insured — confirm this is built into your policy rather than assumed, especially for hired-in equipment.
Who should be named on the CAR policy?
Most contract forms require the employer and contractor to be named as joint insureds, and subcontractors are often added as additional insureds for the works they’re carrying out. Check your specific contract clause rather than relying on a standard policy template.
When does CAR cover need to be in place?
Before site mobilisation. Most contracts require proof of cover before you’re allowed to start work or draw down financing, so insurance arrangements should begin as soon as the Letter of Award is issued — not after.
Get Your CAR Policy Reviewed Before You Mobilise
If you want a second opinion on whether your CAR policy actually matches your contract form and project value, message me on WhatsApp at +6016-336 9321. I work across a multi-provider panel, so the comparison isn’t limited to one insurer’s standard wording.
Disclaimer: This article is for general information only and does not constitute financial, legal, or insurance advice. CAR insurance scope, exclusions, and premium rates vary by insurer, project, and contract form — always confirm specific policy wording with your insurer or broker before relying on it. Keith Wong is a Financial Adviser’s Representative (FAR) and Islamic Financial Adviser’s Representative (IFAR) licensed under Bank Negara Malaysia, and a Licensed Financial Planner (LFP) under the Securities Commission Malaysia. Full credential details are available on the disclaimer page of this website.